
Is MegaPari Legit, Legal or Safe in Saudi Arabia?
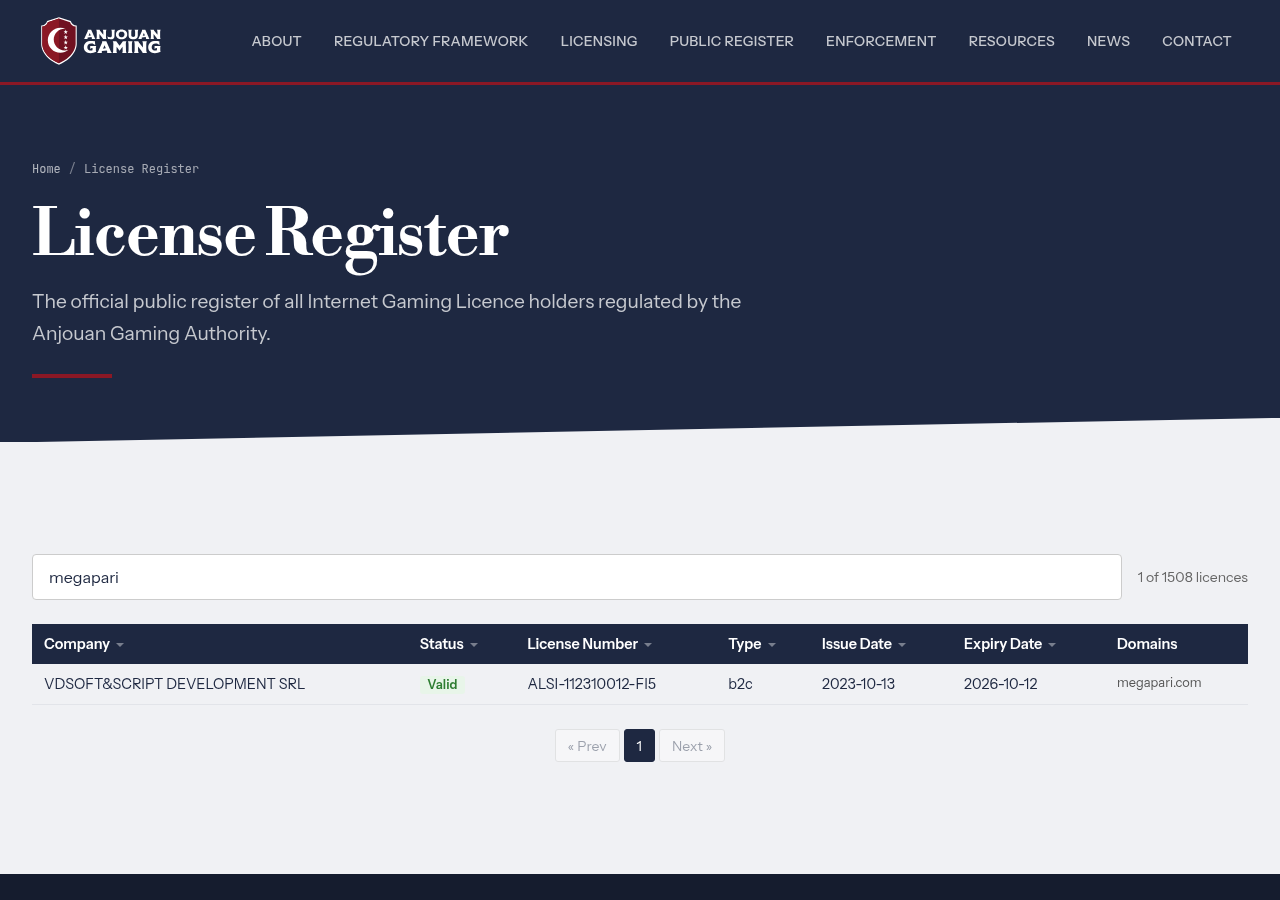
MegaPari has a verifiable Anjouan licence record, but that does not establish Saudi authorisation or guarantee that an account, withdrawal or complaint will have a safe outcome. On 5 September 2026, the Anjouan register showed VDSOFT&SCRIPT DEVELOPMENT SRL, licence ALSI-112310012-FI5, a valid status until 12 October 2026 and megapari.com among the listed domains. The appropriate evidence signal is amber: one precise offshore record is supported, while important legal, payment and individual-outcome questions remain open.
Evidence verdict at a glance
The words “legit”, “legal” and “safe” describe different questions. A matching licence entry can support the identity and offshore licensing status connected with a domain. It cannot, by itself, establish permission in Saudi Arabia, the safety of every transaction or the outcome of a future withdrawal.
| Question | What the available evidence supports | Assessment |
|---|---|---|
| Is there a licence record? | The Anjouan register showed licence ALSI-112310012-FI5 as valid on 5 September 2026, with VDSOFT&SCRIPT DEVELOPMENT SRL and megapari.com in the record. | Supported for that date and record |
| Does that establish Saudi authorisation? | The Saudi Central Bank does not license foreign casino operators. The Anjouan entry is not a Saudi authorisation record. | Not established by the supplied records |
| Are withdrawals guaranteed? | The operator describes possible verification, a connection between deposit and withdrawal methods, and method-dependent timing. | Policy claim only; no guaranteed result |
| Do user reviews prove fraud or safety? | The captured review venue contains mixed reports and operator responses. An individual report does not prove its allegation. | Context only |
An amber signal is deliberately limited. It recognises the current official record without turning that record into a broader endorsement. For a wider explanation of the distinction between foreign records and domestic status, consult the Saudi legal-status guide.
What the Anjouan register establishes
The strongest operator-specific evidence is the Anjouan licence-register entry. When checked on 5 September 2026, it displayed VDSOFT&SCRIPT DEVELOPMENT SRL and licence number ALSI-112310012-FI5. Its status was shown as valid until 12 October 2026, and megapari.com appeared among the domains.
Those details matter because they connect a named company, a numbered licence and a precise domain in a primary register on a stated date. They are more probative than an undated badge, promotional statement or user comment. The date also matters: a status observed on 5 September 2026 describes the register at that check and should not be silently treated as permanent.
| Register field | Recorded detail | Evidence boundary |
|---|---|---|
| Entity | VDSOFT&SCRIPT DEVELOPMENT SRL | Identity shown in the Anjouan record |
| Licence | ALSI-112310012-FI5 | Number displayed by the register |
| Status at check | Valid on 5 September 2026 | Dated observation, not a permanent guarantee |
| Displayed end date | 12 October 2026 | Date shown in the checked record |
| Domain | megapari.com | Exact domain included in the record |
The register does not transform every similarly named address, advertisement or message into the listed domain. A spelling variation or unfamiliar hostname should not be assumed to share the same record. Domain matching is therefore part of the evidence check, not a cosmetic detail.
Saudi legal status: what can and cannot be concluded
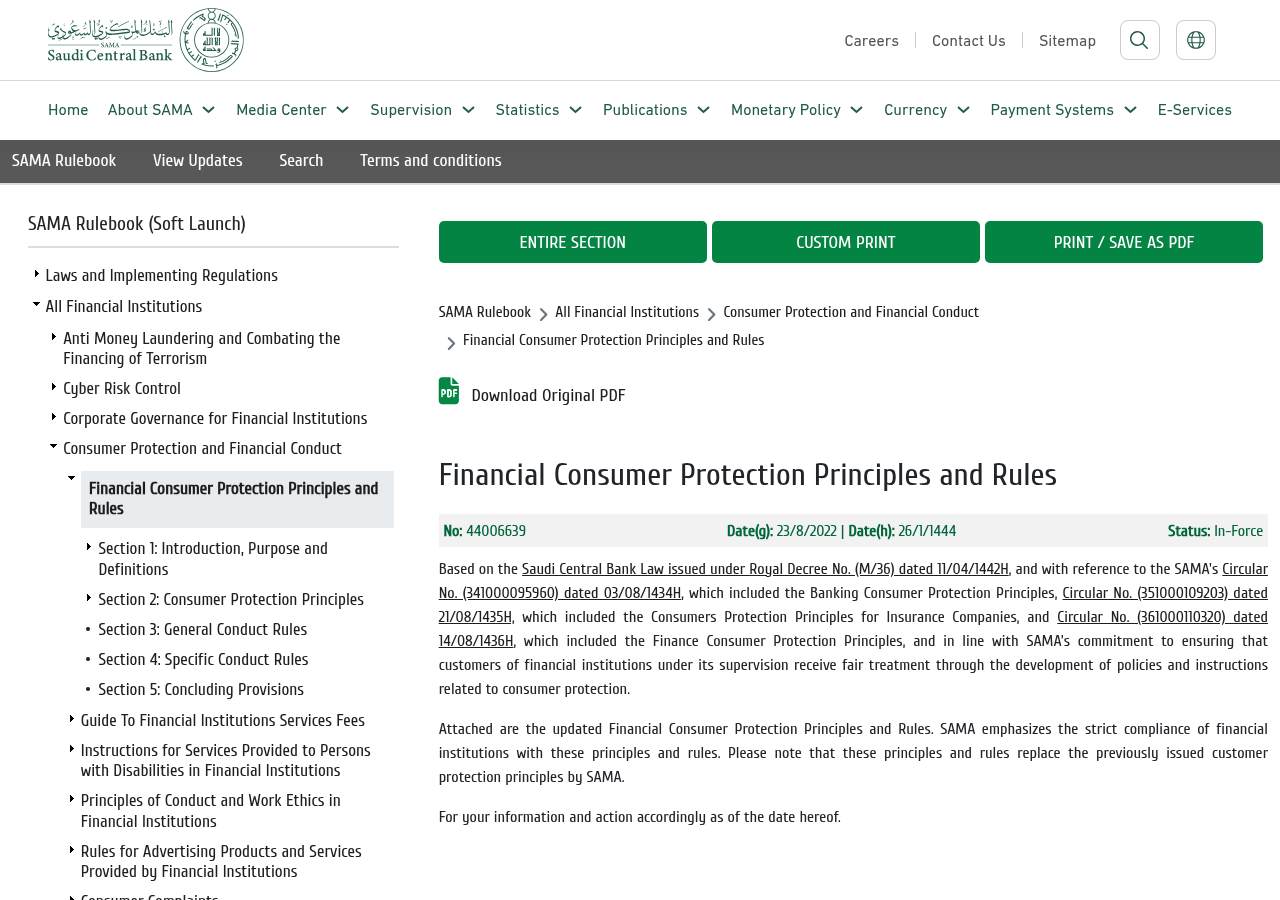
The supplied Saudi Central Bank material defines principles for disclosure, fairness and complaint handling by financial institutions under its supervision. It also establishes an important jurisdictional boundary: the Saudi Central Bank does not license foreign casino operators. Consequently, its consumer-protection framework should not be presented as a casino licence for MegaPari.
The Anjouan record and the Saudi financial-consumer rules answer different questions. The first concerns a foreign licensing entry tied to a company and domain. The second concerns supervised financial institutions and their treatment of financial consumers. Combining them into a claim of Saudi approval would overstate both sources.
The available evidence supports neither a green local-authorisation signal nor a claim that the foreign licence settles Saudi legality. Readers assessing the legal question should keep the jurisdiction, issuing body, named entity, domain and check date separate. The operator evidence directory applies the same record-by-record distinction to other names.
Is MegaPari safe or a scam?
The supplied records do not justify a simple “safe” or “scam” label. The primary licence entry is relevant evidence against treating the name as wholly untraceable, because it identifies an entity, licence number, status and domain. It is not proof that every interaction will be secure, every representation will be accurate or every withdrawal will succeed.
User-report material also requires restraint. The captured Trustpilot venue contains mixed user reports, operator responses and a platform-related notice. Those reports can show that disputes and positive or negative experiences are being described, but no individual post proves the underlying allegation. A review should not be converted into an established finding merely because it is detailed, strongly worded or publicly visible.
| Evidence type | Appropriate use | Inappropriate conclusion |
|---|---|---|
| Primary licence register | Verify the displayed entity, number, status, date and domain | Assume Saudi approval or guaranteed transactions |
| Operator withdrawal guidance | Identify the policy the operator says it applies | Treat the policy as an independently tested outcome |
| User reports | Understand unverified context and disputed experiences | Declare an allegation proven or disproven |
| Saudi official guidance | Understand financial-consumer and cyber-safety routes within their stated scope | Present those bodies as foreign casino licensors |
“Safe” should therefore be broken into narrower checks: whether the exact hostname matches the register, whether a request is consistent with the operator’s stated policy, whether account credentials remain protected, and whether a complaint concerns the operator or a supervised financial institution. None of those checks guarantees an outcome, but each avoids relying on a single broad label.
Official-domain and phishing checks
The licence record specifically included megapari.com. That exact match is the relevant fact; visual resemblance, a familiar name or a message claiming affiliation is not equivalent evidence. Before entering credentials or responding to an account request, compare the full hostname with the domain shown in the primary register rather than relying on a logo or page appearance.
The Saudi National Cybersecurity Authority provides preventive guidance for recognising phishing and protecting accounts. That guidance is useful for evaluating suspicious messages or login requests, but it does not establish that MegaPari—or any other named party—is fraudulent. Cybersecurity advice should remain preventive rather than being treated as an adverse finding.
- Read the complete hostname and compare it with the domain in the dated licence entry.
- Treat unexpected requests for credentials as a cybersecurity issue requiring careful verification.
- Keep account access details protected and avoid treating branding alone as proof of identity.
- Separate a suspicious-message concern from a withdrawal or contractual dispute.
For incident-oriented routes and official distinctions, use the complaints and cybercrime guide. It explains why the recipient of a report depends on what happened, rather than on a broad characterisation of the operator.
Withdrawal policy: verified statement versus actual outcome
MegaPari-controlled withdrawal guidance says that verification may be required. It also says a withdrawal may need to use a method linked to the deposit and that timing depends on the method. These are operator statements describing its announced process. They do not establish a universal processing time, prove that a particular method is available in Saudi Arabia or guarantee completion.
This distinction is especially important when evaluating a pending withdrawal. A stated policy can identify what the operator says may happen, but it does not establish why a specific transaction is delayed. The available evidence contains no independently tested withdrawal outcome. It would therefore be inaccurate to promise speed, claim a standard delay or infer the cause of an individual case.
| Operator statement | What it means | What it does not prove |
|---|---|---|
| Verification may be required | The operator says identity or account checks can form part of withdrawal handling. | That every request is justified or that verification guarantees payment |
| A linked method may be required | The operator says the withdrawal method may need a connection to the deposit method. | That any specific payment method is supported locally |
| Timing depends on the method | The operator does not state one universal duration in the supplied claim. | A precise completion time or outcome for an individual withdrawal |
Before making financial assumptions, review the payment-risk guide. Its purpose is to separate documented transaction facts from expectations that the current evidence cannot support.
Verification and account-lock disputes
A request for verification is consistent with the operator’s published statement that withdrawals may require checks. Consistency with a policy is not the same as proof that a particular account restriction is correct. An account-lock dispute must be evaluated from its own records, including what the user was told, when the restriction appeared and what response followed.
The most useful approach is to preserve exact records rather than compress the dispute into labels such as “scam” or “normal verification”. Retain the account identifier, transaction references, dates, the wording of requests, copies of submitted communications and the operator’s responses. Redact sensitive credentials before sharing a complaint record with any third party.
The 2010 MENAFATF report documents Saudi Arabia’s anti-money-laundering framework, due-diligence concepts and transfers as assessed at that time. Its age and purpose impose clear limits. It is not a casino-licence register, it does not decide a MegaPari account dispute, and it should not be used to claim that a particular verification request is legally required or valid.
Where continued gambling itself is causing concern, the appropriate route is support rather than a commercial destination. The gambling-help resources are separated from operator and payment analysis.
Complaint routes from Saudi Arabia
A complaint should first be classified by its subject. A dispute with an operator is not automatically a complaint against a Saudi-supervised financial institution. Likewise, a suspicious message or credential request is a cybersecurity concern and should not be described as proof of a withdrawal allegation.
The Saudi Central Bank provides an escalation route for a customer complaint against a supervised financial institution after the customer has first initiated the complaint with that institution. That route is relevant only within its stated scope. It is not a foreign-casino complaint adjudication route and should not be represented as one.
| Issue | Relevant evidence route | Scope limit |
|---|---|---|
| Operator withdrawal or account dispute | Preserve the operator correspondence, transaction references and policy wording | The supplied records do not establish an external outcome |
| Complaint against a supervised financial institution | Begin with that institution; the Saudi Central Bank describes escalation after the initial complaint | Applies to supervised financial institutions |
| Suspected phishing or compromised credentials | Use preventive cyber guidance and protect the account | Guidance does not prove a named operator is fraudulent |
| Public review allegation | Treat it as contextual user reporting | It is not an adjudicated fact |
A useful complaint record is chronological and specific. State the transaction or account issue, the date it arose, the response requested and the response received. Avoid claiming that mixed reviews establish the same facts in an individual case. Corrections to the evidence summary can be submitted through the corrections route.
How to assess the evidence before proceeding
The central decision is not whether one source uses reassuring language. It is whether each important claim has the right kind of support. The licence question should be checked against the primary register. Withdrawal expectations should be labelled as operator policy unless an actual outcome is independently documented. User reports should remain contextual. Saudi official sources should be applied only to the responsibilities they actually describe.
- Confirm the exact domain. The dated Anjouan record included megapari.com. Do not substitute a similar hostname.
- Confirm the record date and status. The observed valid status was dated 5 September 2026, with 12 October 2026 displayed as the end date.
- Read withdrawal claims narrowly. Verification, linked-method requirements and timing variation are stated policies, not outcome promises.
- Classify any complaint. Distinguish an operator dispute, a supervised-financial-institution complaint and a cybersecurity concern.
- Keep allegations conditional. Mixed user reporting cannot establish the truth of an individual complaint.
The resulting amber assessment is more informative than a binary endorsement. It confirms what the primary record supports while leaving unresolved matters unresolved. Anyone choosing to continue should do so only after considering the legal-status, payment and domain limitations described above.
rulebook.sama.gov.sa · sama.gov.sa · nca.gov.sa · menafatf.org
Frequently asked questions
Is MegaPari legal in Saudi Arabia?
The available evidence establishes an Anjouan licence entry connected with megapari.com, not Saudi authorisation. The Saudi Central Bank’s consumer rules concern supervised financial institutions, and the Bank does not license foreign casino operators. The evidence therefore supports an amber assessment rather than a claim of local approval.
Does MegaPari have a valid licence?
On 5 September 2026, the Anjouan register showed VDSOFT&SCRIPT DEVELOPMENT SRL and licence ALSI-112310012-FI5 with a valid status until 12 October 2026. The register also included megapari.com among the domains. This is a dated record and should be rechecked when current status matters.
Is megapari.com the official domain in the licence record?
Yes. The Anjouan entry checked on 5 September 2026 included megapari.com among its domains. That precise match does not validate similarly named or visually similar hostnames.
Can MegaPari require verification before a withdrawal?
The operator’s own guidance says a withdrawal may require verification. It also says a method linked to the deposit may be required and timing depends on the method. These are operator policy statements, not an independently tested result or a guarantee of payment.
Do online reviews prove that MegaPari is a scam?
No individual user report proves its allegation. The supplied review capture contains mixed reports, operator responses and a platform-related notice. It is contextual material rather than an official finding, verified complaint outcome or substitute for the primary licence record.
Can I complain to the Saudi Central Bank about MegaPari?
The Saudi Central Bank describes escalation for a customer complaint against a supervised financial institution after the complaint begins with that institution. That route should not be presented as foreign-casino complaint adjudication. First identify whether the issue concerns the operator, a supervised financial institution or cybersecurity.
Does Saudi cybersecurity guidance prove that MegaPari is fraudulent?
No. The National Cybersecurity Authority’s guidance helps people recognise phishing and protect accounts. It is preventive guidance and does not establish that MegaPari, or any other specific entity, is fraudulent.